The German technology sector is recording substantial capital growth in 2026. According to the latest Atomico report on European tech, German start-ups are projected to secure approximately 13.4 billion US dollars in venture capital this year. This represents an 89 percent increase compared to 2025, when funding stood at 7.1 billion dollars. The primary catalyst behind this surge is heavy investment in artificial intelligence, physical robotics, and defense technology. A prominent example is the robotics firm Agile Robots, which finalized a 500 million dollar funding round on November 17, pushing its valuation to 8.5 billion dollars.
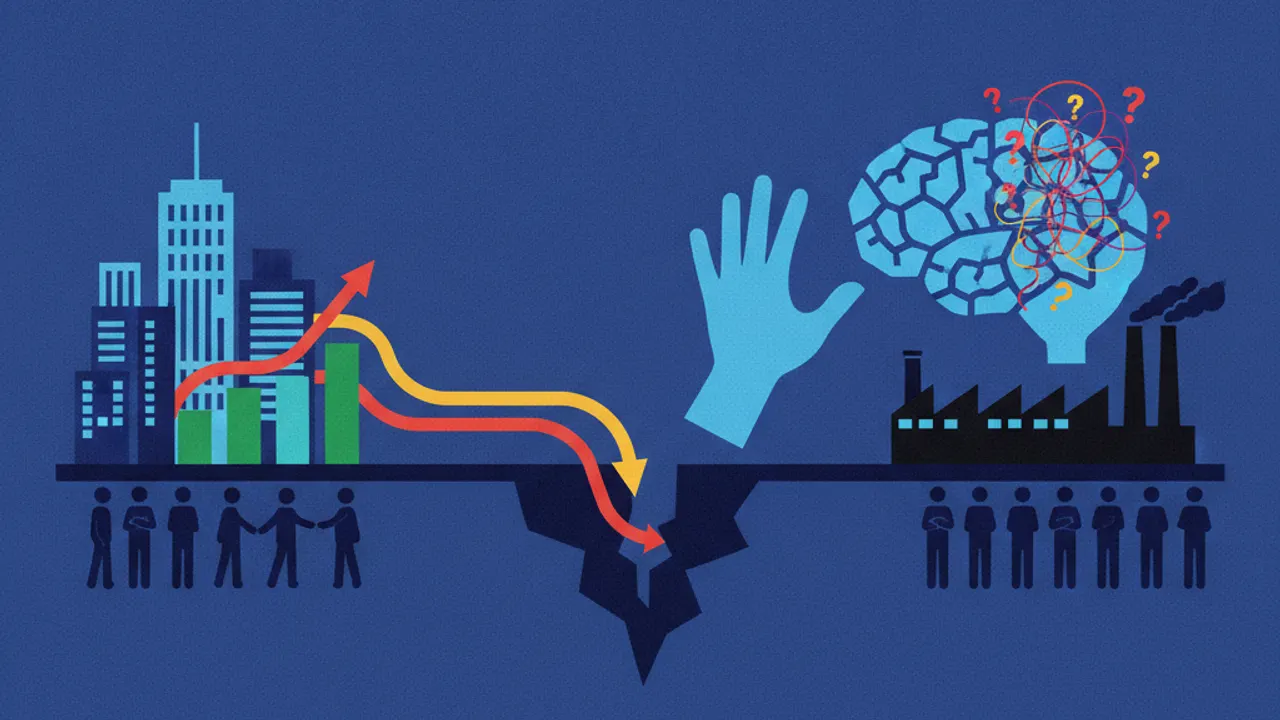
Despite these notable funding rounds, a broader look across the corporate landscape reveals a persistent structural divide. A representative survey conducted by ZEW Mannheim among approximately 1,300 companies illustrates how differently individual economic sectors perceive the technology. In the information economy, 74 percent of surveyed enterprises classify artificial intelligence as very important or important for their competitiveness over the next three years. Specifically, 46 percent rate it as very important, while 28 percent consider it important.
In contrast, the traditional manufacturing sector reports a strikingly different reality. Around 30 percent of industrial companies see little to no impact of artificial intelligence on their competitive standing. Researchers at ZEW also observed that actual deployment within companies strongly correlates with the personal previous experience of executive management. When business leaders lack direct exposure to digital tools, implementation across operational units often stalls entirely.
In parallel, the German Economic Institute in Cologne has identified a significant governance deficit across domestic firms. While roughly 61 percent of enterprises now report using AI tools, adoption typically lacks formal coordination. Only about one third of businesses maintain measurable productivity targets, a dedicated budget, or systematic methods for tracking returns. Especially among mid-sized companies, AI applications remain fragmented single tools rather than integrated business solutions.
This domestic disparity is compounded by an ongoing imbalance in global AI infrastructure. While European AI investments are projected to reach roughly 20 billion euros, this amount remains dwarfed by the US market, which commands 284 billion US dollars. Europe currently accounts for only about 7 percent of global computing capacity. This hardware bottleneck restricts the expansion of local providers and forces enterprises to rely heavily on overseas compute resources.
Meanwhile, the labor market is undergoing a profound structural transformation in skill requirements. Recent Gartner forecasts project that AI will net create 1.7 million jobs worldwide by 2030, while redefining more than 435 million existing roles. In Germany, this shift is causing companies to increasingly defer entry-level hiring while intensifying internal training programs. Organizations now face the urgent challenge of upskilling current staff to manage evolving workflows alongside automated systems.